Stay informed
Stay informed with what’s going on. Browse posts that might be helpful to you or check out an event happening in your area. Come back regularly as this page is kept up-to-date with a lot of relevant information.
🚨 The Retirement Reality Check: Saving vs. Spending
When you are working, your main goal is saving and growing your money.
When you retire, the game completely changes. Growth does not pay for your groceries. Predictable, reliable income does. At this stage, your only major worry is cash flow.
A real retirement plan is not just a passive spreadsheet. It must be a battle tested blueprint. If your plan has not been pushed to its absolute limits, you do not have a plan. You just have a wish list.
What a Strong Retirement Income Plan Looks Like
A safe income plan must be built to survive three major retirement killers:
• The Inflation Surge: If prices go up, your money buys less. Your plan must include income that grows over time, like government pensions or dividend stocks, to protect your lifestyle.
• The Longevity Gamble: If you live past 95, you risk running out of money. A great plan secures guaranteed lifetime income so you can spend confidently without fear of running out.
• The Market Tanking: A severe market crash right when you retire can ruin your portfolio. Your plan needs a safe cash cushion to live off of so you do not have to sell stocks while they are down.
Why Stress Testing is Critical
You would not buy a car that has not passed a crash test. Why trust your life savings to an untested plan?
Stress testing simulates the worst scenarios before they happen.
By testing how your money handles high inflation, long market crashes, and a long life all at once, we find the weak spots today. This lets us build safety nets and fix the issues while you still have time and options.
Do not wait for a market crash to find out if your retirement can survive. Build your plan to last.
Want to see how a resilient plan works?
Click the link below to request a free sample of a stress tested retirement income report. See exactly how we build portfolios to survive inflation, market drops, and a long life.
👇 Get your free sample report here:
He believes he has completed his estate planning.
However, after an unexpected medical event, he becomes incapable of managing his financial affairs or making certain personal care decisions.
His family discovers that having a Will does not automatically give them authority to make decisions on his behalf while he is alive.
Important lessons:
1. A Will generally deals with the distribution of your estate after death.
2. A Power of Attorney for Property addresses financial and property decisions during your lifetime.
3. A Power of Attorney for Personal Care addresses personal care decisions if you become incapable.
These documents serve different purposes.
Estate planning should consider both life and death.
Speak to a competent lawyer today. Let me know if you need help finding a lawyer.
He believes he has completed his estate planning.
However, after an unexpected medical event, he becomes incapable of managing his financial affairs or making certain personal care decisions.
His family discovers that having a Will does not automatically give them authority to make decisions on his behalf while he is alive.
Important lessons:
1. A Will generally deals with the distribution of your estate after death.
2. A Power of Attorney for Property addresses financial and property decisions during your lifetime.
3. A Power of Attorney for Personal Care addresses personal care decisions if you become incapable.
These documents serve different purposes.
Estate planning should consider both life and death.
Speak to a competent lawyer today. Let me know if you need help finding a lawyer.
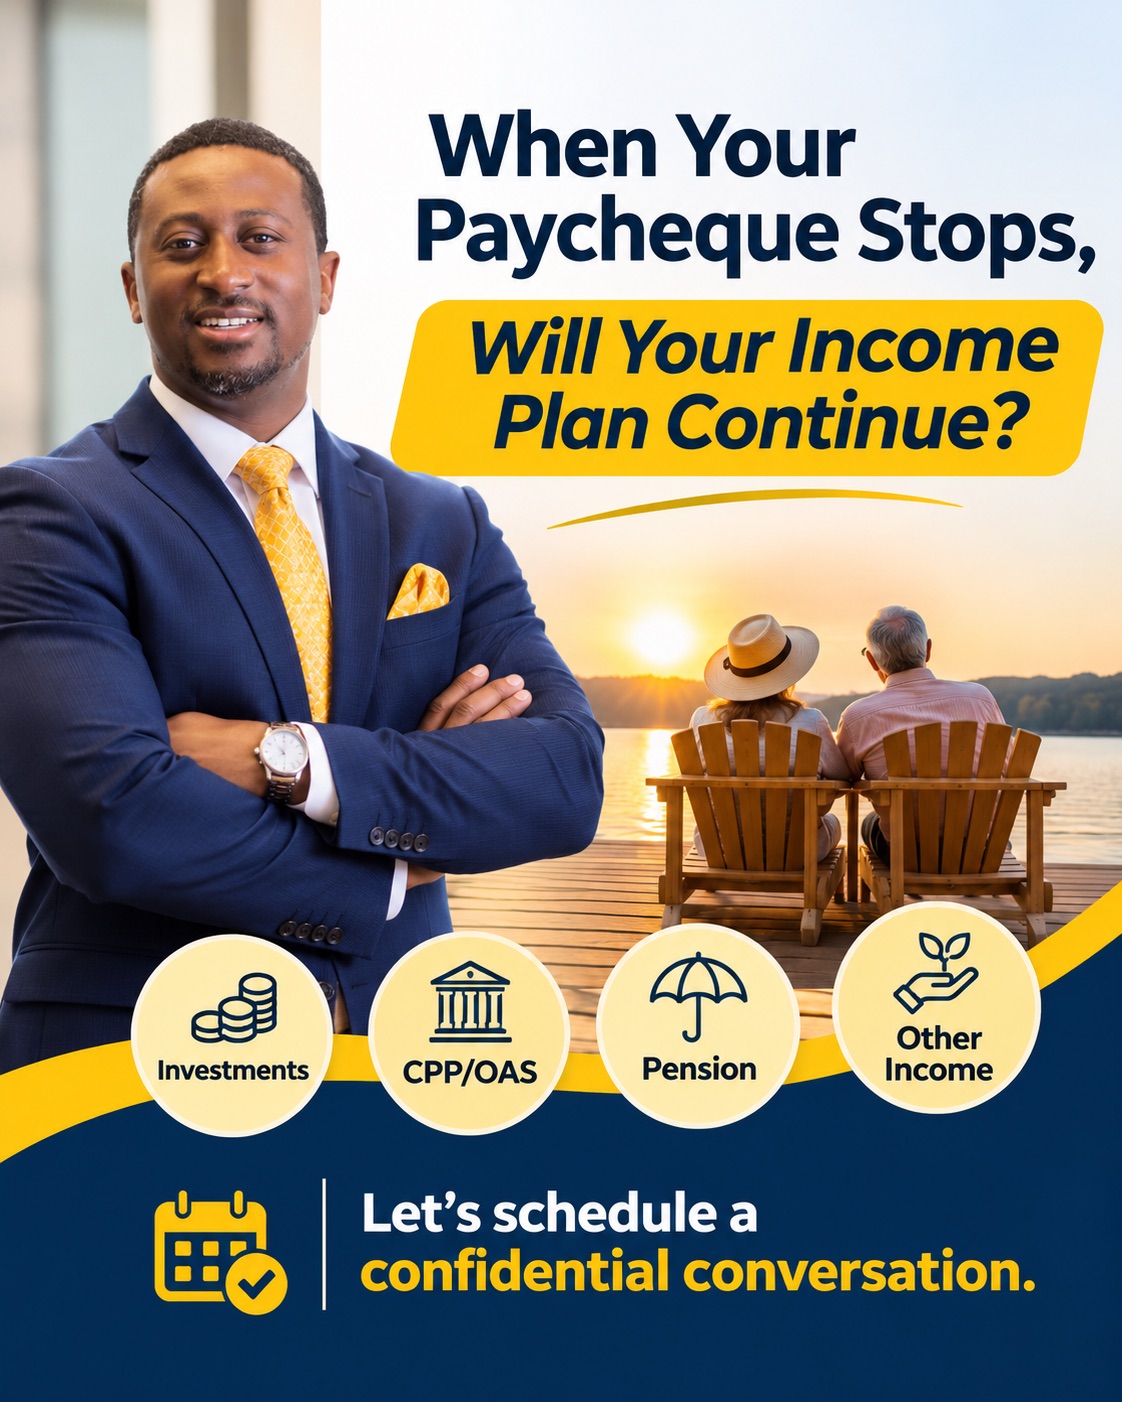
You know when your next paycheque is coming today. But do you know where your income will come from when you retire?
During your working years, income often comes from employment or business activities.
In retirement, things may look different.
You may need to coordinate:
Personal investments.
RRSP and RRIF withdrawals.
TFSA savings.
Pension income.
CPP and OAS benefits.
Other sources of income.
A well considered retirement income strategy can help you understand how these resources may work together.
Your retirement deserves more than assumptions. Let's discuss how you can prepare for the transition.
You know when your next paycheque is coming today. But do you know where your income will come from when you retire?
During your working years, income often comes from employment or business activities.
In retirement, things may look different.
You may need to coordinate:
Personal investments.
RRSP and RRIF withdrawals.
TFSA savings.
Pension income.
CPP and OAS benefits.
Other sources of income.
A well considered retirement income strategy can help you understand how these resources may work together.
Your retirement deserves more than assumptions. Let's discuss how you can prepare for the transition.
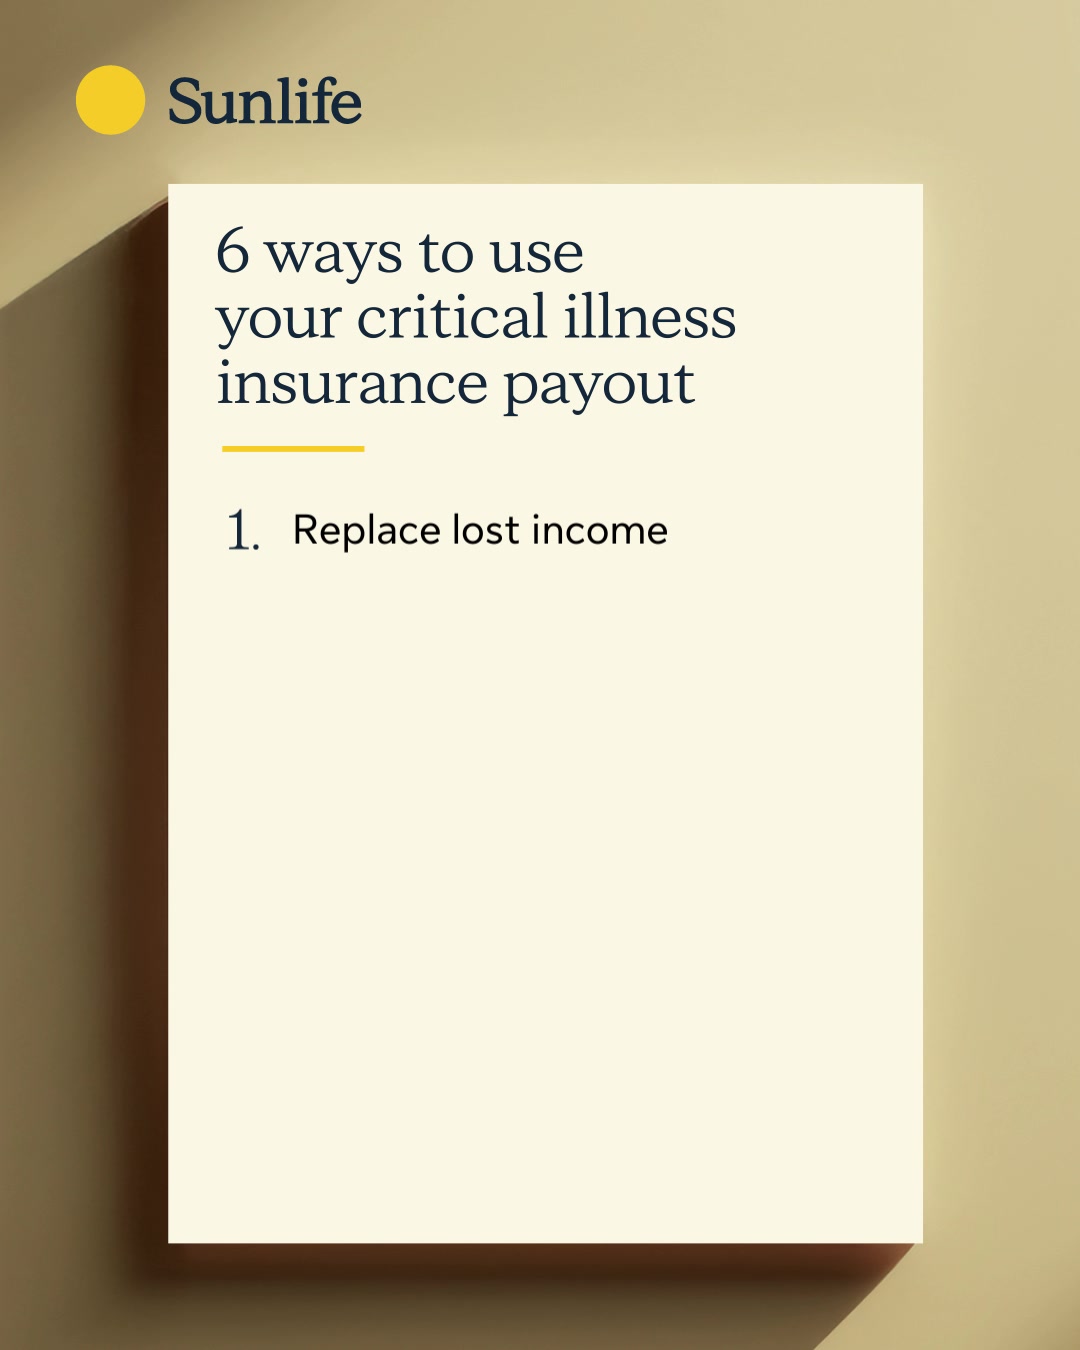
6 ways to use your critical illness insurance payout
That’s where critical illness insurance can help. The payout is yours to use based on what you need most. And for a limited time, when you bundle CII with an eligible life insurance policy, you'll receive a 10% discount on the CII premiums for the life of the policy.*
Why bundle CII with life insurance?
• Life insurance helps protect your loved ones when you’re gone.
• Critical illness insurance helps protect you and your loved ones while you’re still here.
https://www.sunlife.ca/en/lclp/ciioffer-advisor-share/?WT.mc_id=en-ca%3Asocial%3Anetworks%3Ayext%3Aadvisor
Reach out if you’d like to learn more.
*Terms and conditions apply.
Having retirement savings is important. However, knowing how to turn those savings into income is another important part of retirement planning.
Your RRSP, TFSA, non-registered investments, workplace pension and government benefits may all play different roles.
The real question is: How will these resources work together to support the lifestyle you want?
Retirement planning should go beyond accumulating money. It should also consider how you will use it.
Let's schedule a confidential conversation to explore how your retirement savings could support your future income needs.
Having retirement savings is important. However, knowing how to turn those savings into income is another important part of retirement planning.
Your RRSP, TFSA, non-registered investments, workplace pension and government benefits may all play different roles.
The real question is: How will these resources work together to support the lifestyle you want?
Retirement planning should go beyond accumulating money. It should also consider how you will use it.
Let's schedule a confidential conversation to explore how your retirement savings could support your future income needs.
Because he is not married and has no children, he believes estate planning can wait until later in life.
Unfortunately, he has overlooked an important issue: what happens to his assets and personal affairs if he passes away without a Will?
Without a valid Will, his estate may be distributed according to applicable provincial intestacy laws rather than his personal wishes.
Important lessons:
Being single does not eliminate the need for estate planning. You may have family members, friends or charitable causes you wish to benefit.
A Will allows you to document your wishes.
You should consider who will manage your estate and your marital status does not determine whether you need an estate.
Reach out if you need help finding a competent lawyer!
Because he is not married and has no children, he believes estate planning can wait until later in life.
Unfortunately, he has overlooked an important issue: what happens to his assets and personal affairs if he passes away without a Will?
Without a valid Will, his estate may be distributed according to applicable provincial intestacy laws rather than his personal wishes.
Important lessons:
Being single does not eliminate the need for estate planning. You may have family members, friends or charitable causes you wish to benefit.
A Will allows you to document your wishes.
You should consider who will manage your estate and your marital status does not determine whether you need an estate.
Reach out if you need help finding a competent lawyer!
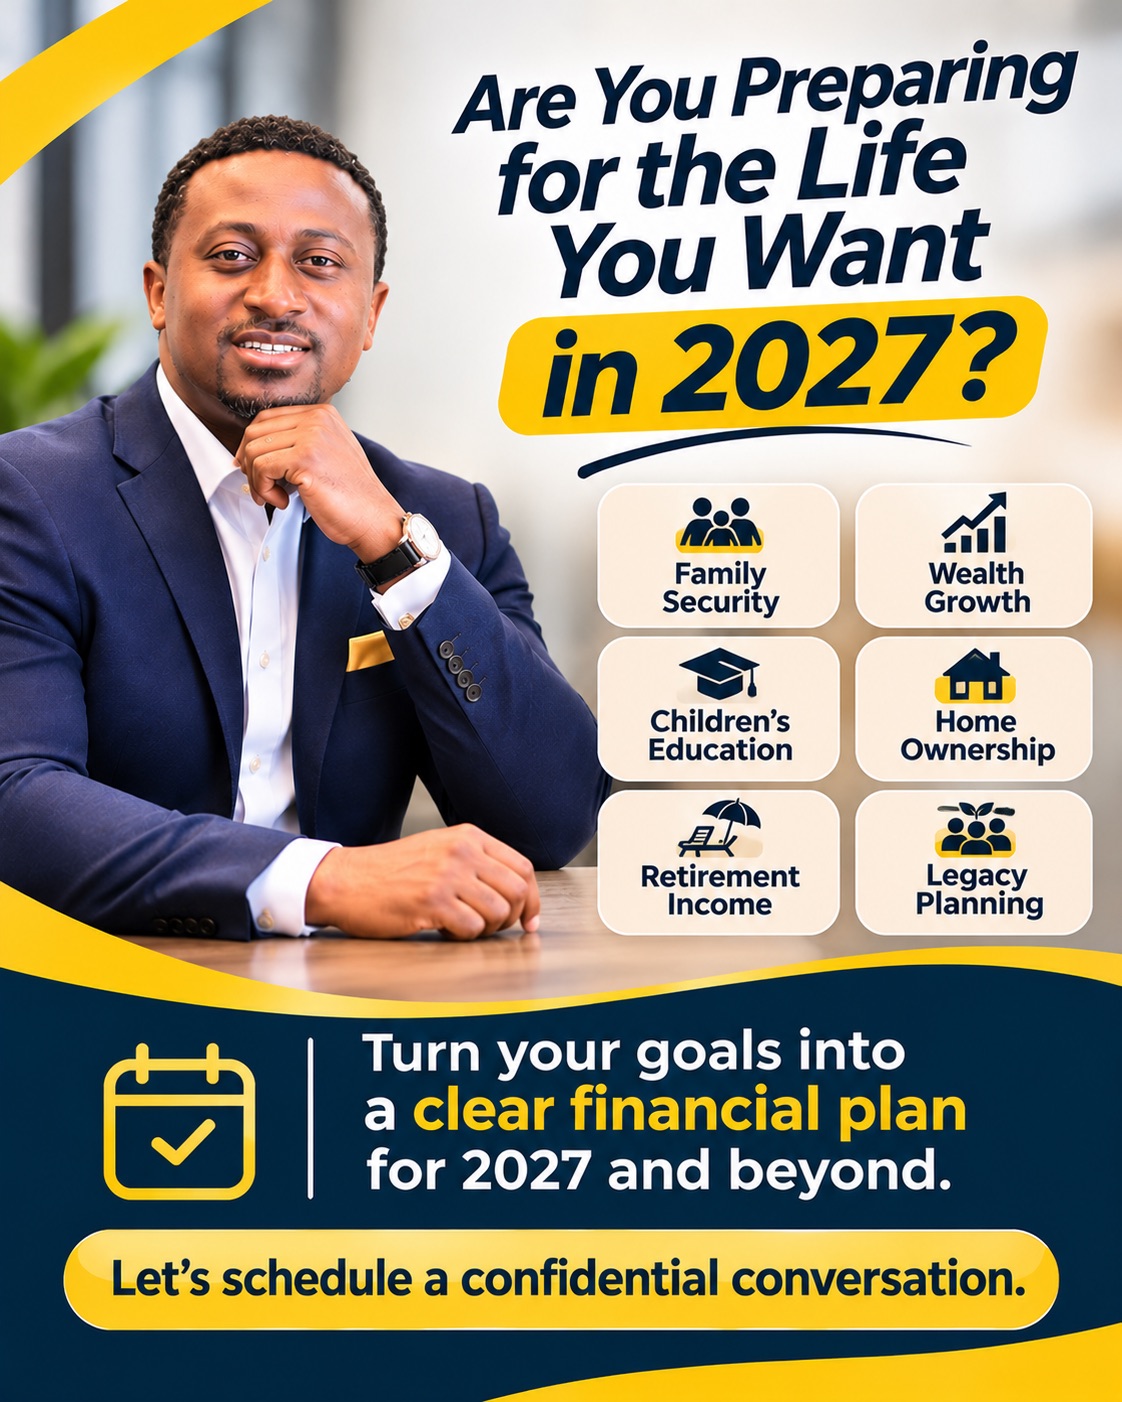
Before the new year begins, take a moment to think about what you and your family want to accomplish.
Is it:
* Building your savings?
* Incorporating your practice?
* Buying your first or next home?
* Planning for your children’s education?
* Growing your investments?
* Protecting your family’s financial future?
* Preparing for retirement?
Dreams are important. But having clarity about what you want to accomplish is an important starting point.
My role is to understand your financial goals, help you map out the possibilities, and share options that may support your journey.
Don’t just enter 2027 with wishes. Enter with clarity.
Let’s schedule a confidential conversation and find out how we can help you explore your financial goals.
Before the new year begins, take a moment to think about what you and your family want to accomplish.
Is it:
* Building your savings?
* Incorporating your practice?
* Buying your first or next home?
* Planning for your children’s education?
* Growing your investments?
* Protecting your family’s financial future?
* Preparing for retirement?
Dreams are important. But having clarity about what you want to accomplish is an important starting point.
My role is to understand your financial goals, help you map out the possibilities, and share options that may support your journey.
Don’t just enter 2027 with wishes. Enter with clarity.
Let’s schedule a confidential conversation and find out how we can help you explore your financial goals.
What’s the difference between critical illness insurance and life insurance?
Many people understand the importance of life insurance. Fewer understand how critical illness insurance can help support them while they're still here.
Life insurance can help protect the people you love if you're no longer there to provide for them. Critical illness insurance may help provide financial support if you're diagnosed with a covered condition and need time to focus on recovery.
Understanding the difference is an important step toward building a more complete protection strategy.
Learn more about how life insurance and critical illness insurance compare and reach out if you'd like to discuss what makes sense for your situation.
https://www.sunlife.ca/en/health/critical-illness-insurance/critical-illness-insurance-vs-life-insurance/?WT.mc_id=en-ca%3Asocial%3Anetworks%3Ayext%3Aadvisor
A financial roadmap isn't about chasing wealth for the sake of it. It's about giving yourself the confidence to focus on what matters most today while preparing for tomorrow.
Some of life's best moments aren't things you buy. They're moments you're fully present for.
Let's start building your financial roadmap together.
A financial roadmap isn't about chasing wealth for the sake of it. It's about giving yourself the confidence to focus on what matters most today while preparing for tomorrow.
Some of life's best moments aren't things you buy. They're moments you're fully present for.
Let's start building your financial roadmap together.
But preserving what you've grown and ensuring it benefits future generations often requires a different conversation.
From tax-efficient strategies and retirement considerations to protecting assets and creating a legacy, the choices you make today can influence what your wealth can accomplish tomorrow.
Let's connect to discuss your goals. https://advisor.sunlife.ca/isaac.oluwagbemi/
But preserving what you've grown and ensuring it benefits future generations often requires a different conversation.
From tax-efficient strategies and retirement considerations to protecting assets and creating a legacy, the choices you make today can influence what your wealth can accomplish tomorrow.
Let's connect to discuss your goals. https://advisor.sunlife.ca/isaac.oluwagbemi/
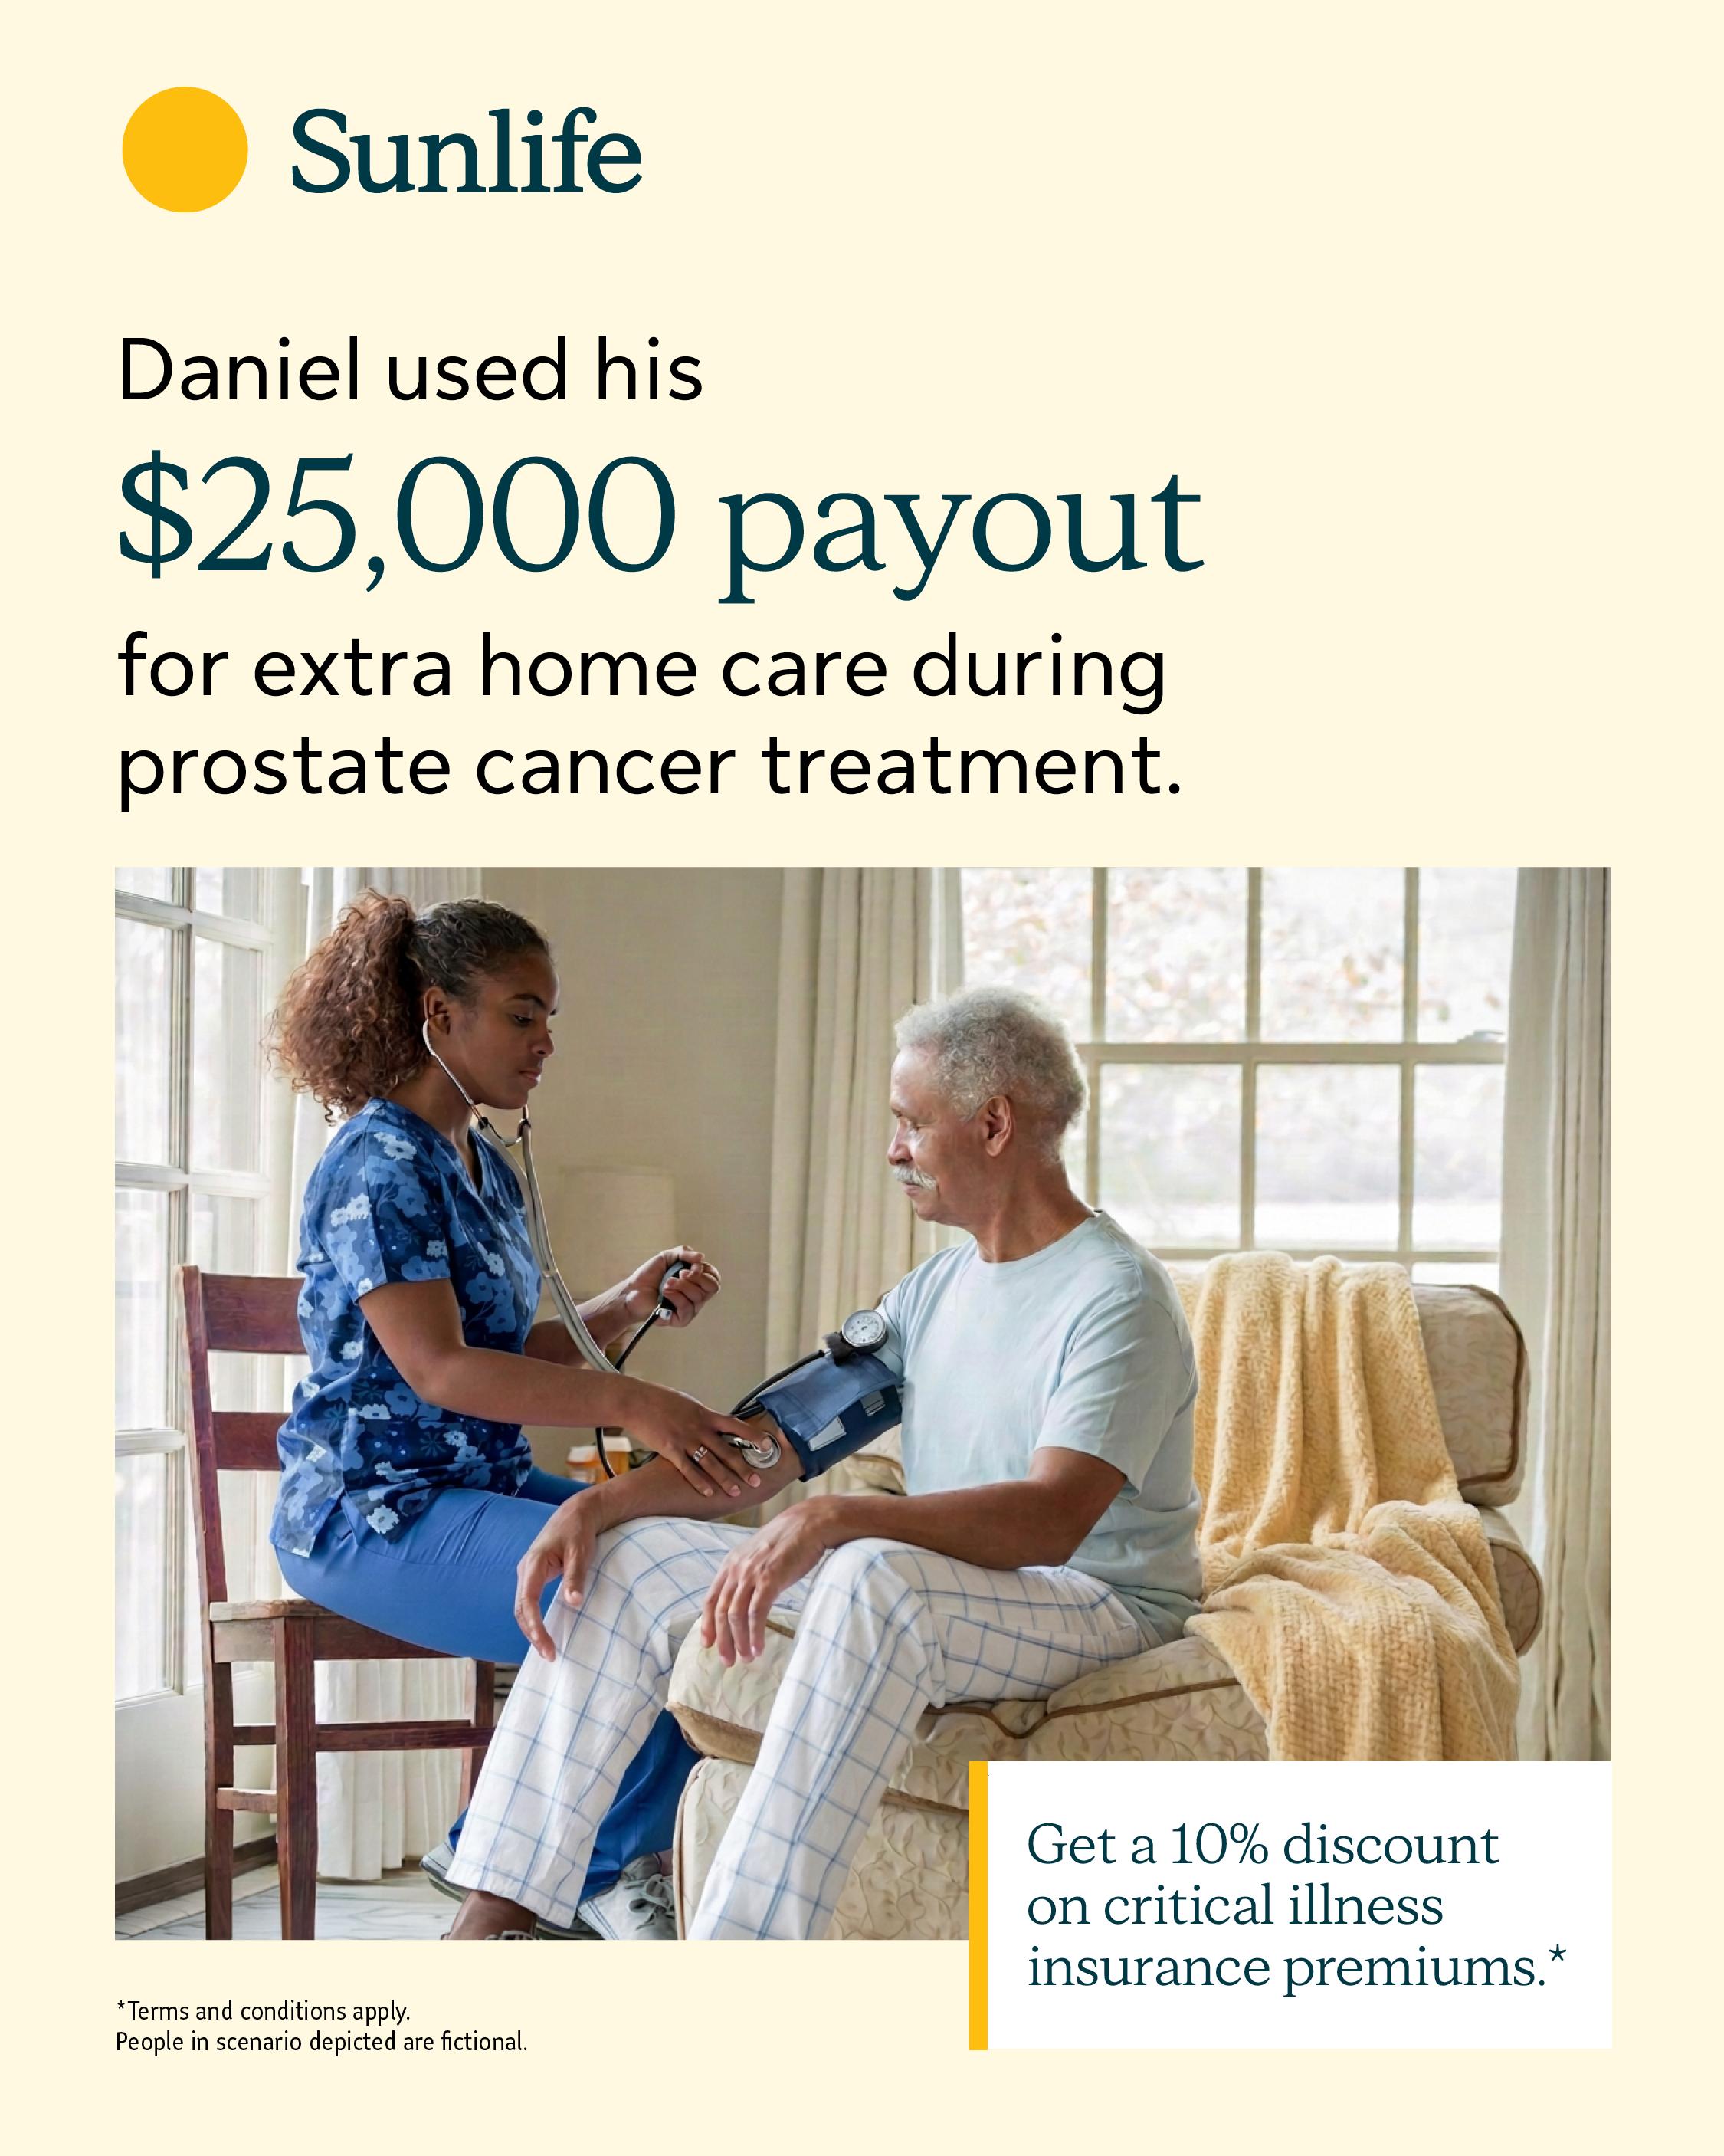
Your payout could help you:
• Replace lost income
• Take time off to recover
• Pay for help at home
• Cover treatment and travel costs
• Stay on top of bills and debt
• Keep your savings and assets
For a limited time, you can receive a 10% premium discount on CII when you bundle it with eligible life insurance.*
See how this offer could help you get more protection for less.
*Terms and conditions apply.
Your payout could help you:
• Replace lost income
• Take time off to recover
• Pay for help at home
• Cover treatment and travel costs
• Stay on top of bills and debt
• Keep your savings and assets
For a limited time, you can receive a 10% premium discount on CII when you bundle it with eligible life insurance.*
See how this offer could help you get more protection for less.
*Terms and conditions apply.
The reality is that life is unpredictable.
Critical considerations for your long-term security:
• Income Protection: If you were suddenly unable to earn an income, what would happen to your family's commitments?
• Major Obligations: Would critical expenses like your mortgage, your children's education, and daily living costs remain manageable? If yes, for how long?
• Risk Management: Proactively evaluating insurance options is the most effective way to insulate your household from sudden financial distress.
For many, waiting until tomorrow is simply too late.
Protecting your long-term financial goals begins with identifying and mitigating your risks today.
Please feel free to reach out if you have any questions or would like to discuss your options.
The reality is that life is unpredictable.
Critical considerations for your long-term security:
• Income Protection: If you were suddenly unable to earn an income, what would happen to your family's commitments?
• Major Obligations: Would critical expenses like your mortgage, your children's education, and daily living costs remain manageable? If yes, for how long?
• Risk Management: Proactively evaluating insurance options is the most effective way to insulate your household from sudden financial distress.
For many, waiting until tomorrow is simply too late.
Protecting your long-term financial goals begins with identifying and mitigating your risks today.
Please feel free to reach out if you have any questions or would like to discuss your options.
Remembrance Day is an opportunity to honour the courage, service, and sacrifices of those who have served our country, and to recognize the lasting impact they have made.
As we observe a moment of reflection, we express our gratitude to veterans, active service members, and their families for their dedication and commitment.
Lest we forget.
#RemembranceDay #LestWeForget
Remembrance Day is an opportunity to honour the courage, service, and sacrifices of those who have served our country, and to recognize the lasting impact they have made.
As we observe a moment of reflection, we express our gratitude to veterans, active service members, and their families for their dedication and commitment.
Lest we forget.
#RemembranceDay #LestWeForget
From changes that could help with everyday costs to new housing, tax and benefit measures, there’s a lot to unpack.
Take a look at what’s in Budget 2026 and what some of the changes could mean for you. https://www.sunlife.ca/en/investments/canada-federal-budget/?WT.mc_id=en-ca%3Asocial%3Anetworks%3Ayext%3Aadvisor
If you have questions about how they may relate to your financial goals, let’s connect.
From changes that could help with everyday costs to new housing, tax and benefit measures, there’s a lot to unpack.
Take a look at what’s in Budget 2026 and what some of the changes could mean for you. https://www.sunlife.ca/en/investments/canada-federal-budget/?WT.mc_id=en-ca%3Asocial%3Anetworks%3Ayext%3Aadvisor
If you have questions about how they may relate to your financial goals, let’s connect.
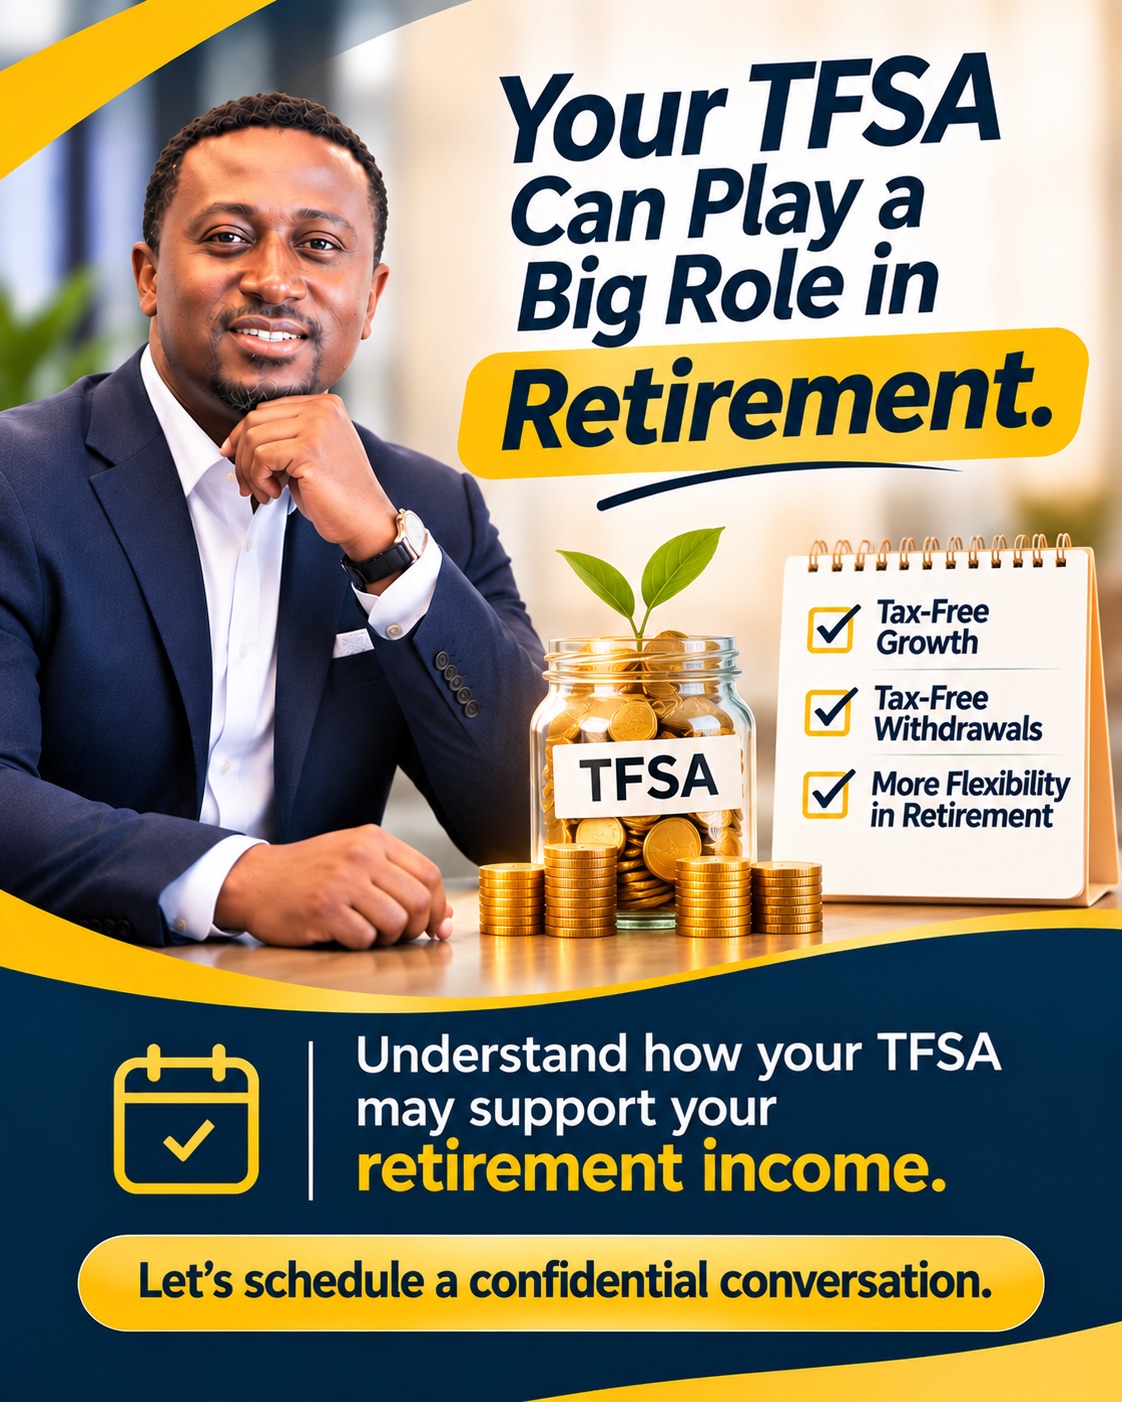
A Tax-Free Savings Account (TFSA) is not limited to short-term savings. Eligible investments held inside a TFSA can grow tax-free, and withdrawals are generally tax-free under Canadian tax rules.
Unlike RRSP withdrawals, TFSA withdrawals generally do not count as taxable income. However, contribution limits, eligibility, and individual circumstances matter. These differences make it useful to understand how a TFSA compares with other registered accounts.
Do you understand how the tax treatment of your accounts differs?
Let’s schedule a confidential conversation to discuss your retirement income and lifestyle.
A Tax-Free Savings Account (TFSA) is not limited to short-term savings. Eligible investments held inside a TFSA can grow tax-free, and withdrawals are generally tax-free under Canadian tax rules.
Unlike RRSP withdrawals, TFSA withdrawals generally do not count as taxable income. However, contribution limits, eligibility, and individual circumstances matter. These differences make it useful to understand how a TFSA compares with other registered accounts.
Do you understand how the tax treatment of your accounts differs?
Let’s schedule a confidential conversation to discuss your retirement income and lifestyle.
A personalized financial strategy can help you plan for retirement, protect your family, and build the financial confidence you deserve.
Let's work together to create your path forward. https://advisor.sunlife.ca/isaac.oluwagbemi/
A personalized financial strategy can help you plan for retirement, protect your family, and build the financial confidence you deserve.
Let's work together to create your path forward. https://advisor.sunlife.ca/isaac.oluwagbemi/
It is also about preparing for unexpected events.
What would happen to your family's financial commitments if you could no longer earn an income?
Would your mortgage, children's education and other obligations be manageable?
There are different insurance and risk management options worth exploring, depending on your circumstances.
Protecting your financial dreams starts with understanding the risks.
Think about it and put necessary plan in place.
It is also about preparing for unexpected events.
What would happen to your family's financial commitments if you could no longer earn an income?
Would your mortgage, children's education and other obligations be manageable?
There are different insurance and risk management options worth exploring, depending on your circumstances.
Protecting your financial dreams starts with understanding the risks.
Think about it and put necessary plan in place.

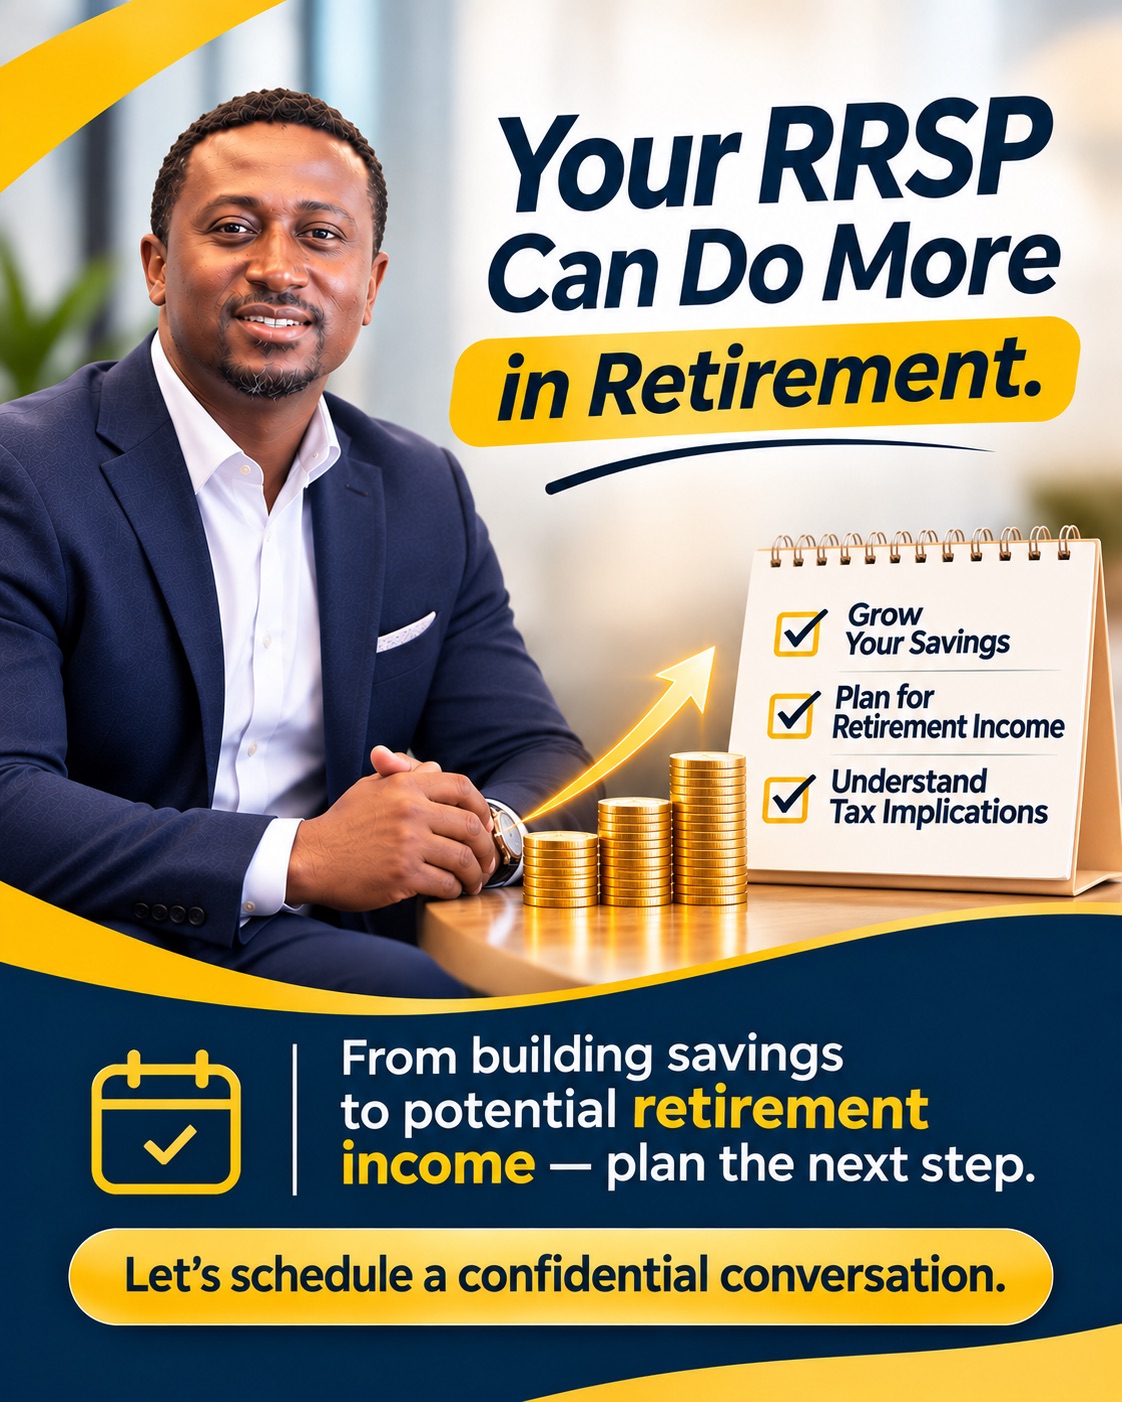
But what happens when you retire and begin using those savings?
That is when questions about withdrawals, taxes, and retirement income options become increasingly important.
For example, an RRSP generally must be converted to a permitted retirement income option or withdrawn by the end of the year you turn 71, subject to applicable rules.
Understanding the transition from saving to drawing income is an important part of retirement planning.
Ask yourself: Have you considered how your RRSP may contribute to your future retirement income?
Your retirement income deserves a plan.
Let’s schedule a confidential conversation to discuss your retirement goals and explore the questions that matter to you.
But what happens when you retire and begin using those savings?
That is when questions about withdrawals, taxes, and retirement income options become increasingly important.
For example, an RRSP generally must be converted to a permitted retirement income option or withdrawn by the end of the year you turn 71, subject to applicable rules.
Understanding the transition from saving to drawing income is an important part of retirement planning.
Ask yourself: Have you considered how your RRSP may contribute to your future retirement income?
Your retirement income deserves a plan.
Let’s schedule a confidential conversation to discuss your retirement goals and explore the questions that matter to you.
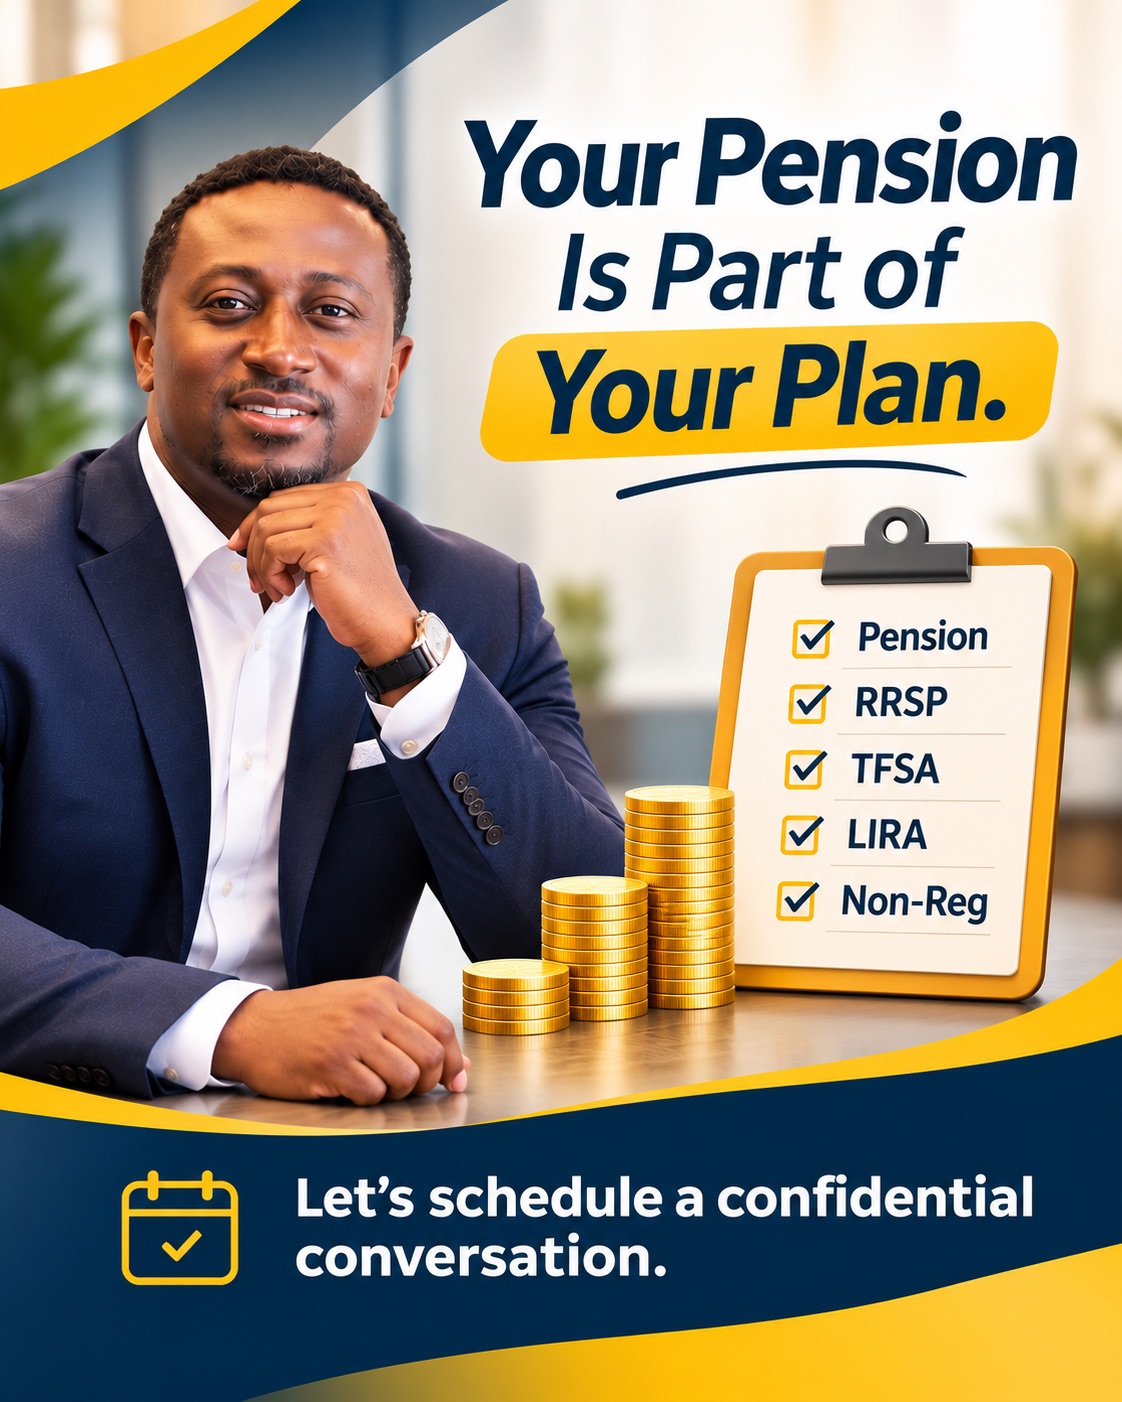
But have you considered how your pension fits with your other financial resources?
Pension arrangements differ. Your benefits may depend on your plan, years of service, retirement age, and other provisions.
Your RRSP, TFSA, LIRA, non-registered investments, and other potential income sources may also form part of your overall retirement picture.
The goal of retirement education is to understand the different pieces and the role each may play.
Ask yourself: Do you understand what your pension may provide and what other income sources you may need to consider?
Your retirement income deserves a plan.
Let’s schedule a confidential conversation to discuss your retirement goals and explore the questions that matter to you.
But have you considered how your pension fits with your other financial resources?
Pension arrangements differ. Your benefits may depend on your plan, years of service, retirement age, and other provisions.
Your RRSP, TFSA, LIRA, non-registered investments, and other potential income sources may also form part of your overall retirement picture.
The goal of retirement education is to understand the different pieces and the role each may play.
Ask yourself: Do you understand what your pension may provide and what other income sources you may need to consider?
Your retirement income deserves a plan.
Let’s schedule a confidential conversation to discuss your retirement goals and explore the questions that matter to you.
An annuity helps turn your savings into guaranteed income for life. No surprises. No stress. Just steady support when you need it most.
Let's talk about your retirement roadmap.
An annuity helps turn your savings into guaranteed income for life. No surprises. No stress. Just steady support when you need it most.
Let's talk about your retirement roadmap.
Have questions?
Here to help answer your questions, provide clarity about products and get you started on the road to achieving your goals.